This article applies to the following countries
- Sweden
New entertainment types
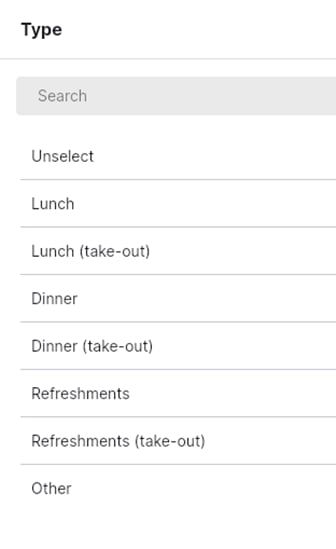
Food for takeaway has a new VAT rate of 6%. To simplify reporting takeaway entertainment we have added three new types:- Lunch (takeaway)
- Dinner (takeaway)
- Refreshments (takeaway)
Takeaway and catering (no alcohol) – 6% VAT
For entertainment involving takeaway or catering (without additional services) and no alcohol, the 6% VAT rate applies. We recognise this rate and allow deductions up to a maximum of SEK 18 per person (6% of the SEK 300 net limit per person). Entertainment types Each entertainment category can use one or more types of entertainment. With 6% VAT, all types can be used, but we recommend the takeaway types.- Lunch (takeaway)
- Dinner (takeaway)
- Refreshments (takeaway)
- Lunch
- Dinner
- Refreshments
Restaurant meals (no alcohol) – 12% VAT
For restaurant entertainment without alcohol, the VAT rate is 12%.We allow deductions up to a maximum of SEK 36 per person (12% of the SEK 300 net limit per person). Do not use “takeaway” types if the receipt shows 12% VAT. Entertainment types Each entertainment category can use one or more types of entertainment. With 12% VAT you should not use takeaway.- Lunch
- Dinner
- Refreshments
Restaurant meals with alcohol
The VAT rules remain unchanged here: 12% VAT on food and 25% VAT on alcohol (or other 25% goods). Flat-rate (Schablon): A flat-rate deduction of SEK 46 per person is applied automatically whenever it is more favourable. Entertainment types Each entertainment category can use one or more types of entertainment. With 12% VAT you should not use takeaway.- Lunch
- Dinner
- Refreshments
Mixed VAT rates: 6% and 25% VAT (e.g., Catering with alcohol)
If catering includes alcohol, or if takeaway food is combined with 25% VAT items, the VAT will consist of both 6% and 25%. We handle this in a few different ways:- If the user selects takeaway, we know that the entertainment expense is based on 6% VAT. We apply logic that automatically uses the SEK 33 per person flat-rate if it is beneficial.
- If the user selects a standard entertainment type and the VAT amount is between 6% and 12%, we show an information message about mixed VAT rates, and that it could be useful to split the purchase in two or more expenses. Splitting the expense is not mandatory; see it as a recommendation.
- Lunch (takeaway)
- Dinner (takeaway)
- Refreshments (takeaway)
- Lunch
- Dinner
- Refreshments
Mixed VAT rates: 12% and 25% VAT
If the entertainment expense is for Meals with alcohol in a restaurant, the VAT amount will be made up of both 12% and 25% VAT. See Restaurant meals with alcohol above. Mixed 6%, 12%, and 25% VAT In theory, it is possible to make a purchase involving all three VAT rates: 6%, 12%, and 25%. In practice, this is unlikely to happen, but if it does, the purchase should be split into multiple expenses.For example:- Lunch at a restaurant with food and alcohol, plus takeaway food for internal entertainment at the office: 6%, 12%, and 25%.
- One expense with 6% VAT for the items taken back to the office.
- One expense with 12% and 25% VAT for the restaurant visit.
Summary
- Only 6% VAT: Create an expense; use takeaway types for correct deductions.
- Only 12% VAT: Create an expense; do not use takeaway types.
- Catering with alcohol: Create an expense; use takeaway types.
- Food and alcohol in a restaurant: Create an expense, do not use takeaway types.
- Other combinations: Use the “Split receipt” function to divide the purchase into two or more expenses.