> ## Documentation Index
> Fetch the complete documentation index at: https://help.findity.com/llms.txt
> Use this file to discover all available pages before exploring further.
# Business Representation and VAT from April 1, 2026
**This article applies to the following countries**
* Sweden
From 1 April, the VAT rate on food will be reduced to **6%**, except for food served in restaurants and similar establishments, where the VAT rate remains at **12%**.
This change leads to some adjustments regarding entertainment expenses. The Swedish Tax Agency (Skatteverket) has published new rules, and we have implemented them. There are, however, some peculiarities in the regulations.
The fundamental issue is that with three different VAT rates, it is impossible to calculate which specific rates are included in a total VAT amount. Therefore, users and administrators must manually specify the type of entertainment involved.
This document describes our implementation and best practices when creating entertainment expenses.
### New entertainment types
Food for takeaway has a new VAT rate of **6%**. To simplify reporting takeaway entertainment we have added three new types:
* Lunch (takeaway)
* Dinner (takeaway)
* Refreshments (takeaway)
Selecting these types activates the calculation logic for **6%** VAT.
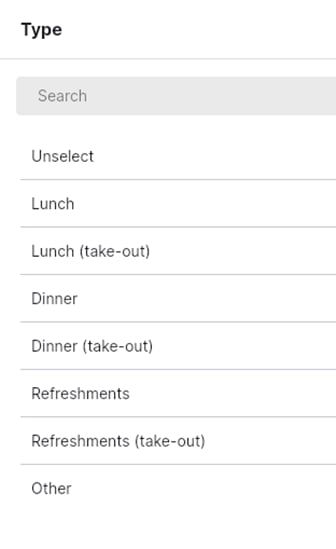 *All types of entertainment for Swedish companies*
### Takeaway and catering (no alcohol) – 6% VAT
For entertainment involving takeaway or catering (without additional services) and no alcohol, the **6%** VAT rate applies. We recognise this rate and allow deductions up to a maximum of **SEK 18 per person** (**6%** of the SEK 300 net limit per person).
**Entertainment types**
Each entertainment category can use one or more types of entertainment. With **6%** VAT, all types can be used, but we recommend the takeaway types.
* **Lunch (takeaway)**
* **Dinner (takeaway)**
* **Refreshments (takeaway)**
* Lunch
* Dinner
* Refreshments
### Restaurant meals (no alcohol) – 12% VAT
For restaurant entertainment without alcohol, the VAT rate is **12%**.We allow deductions up to a maximum of **SEK 36 per person** (**12%** of the SEK 300 net limit per person). Do not use "takeaway" types if the receipt shows **12%** VAT.
**Entertainment types**
Each entertainment category can use one or more types of entertainment. With **12%** VAT you should not use takeaway.
* Lunch
* Dinner
* Refreshments
### Restaurant meals with alcohol
The VAT rules remain unchanged here: **12%** VAT on food and **25%** VAT on alcohol (or other **25%** goods).
**Flat-rate (Schablon):** A flat-rate deduction of **SEK 46 per person** is applied automatically whenever it is more favourable.
**Entertainment types**
Each entertainment category can use one or more types of entertainment. With **12%** VAT you should not use takeaway.
* Lunch
* Dinner
* Refreshments
### Mixed VAT rates: 6% and 25% VAT (e.g., Catering with alcohol)
If catering includes alcohol, or if takeaway food is combined with **25%** VAT items, the VAT will consist of both **6%** and **25%**.
**We handle this in a few different ways:**
* If the user selects takeaway, we know that the entertainment expense is based on **6%** VAT. We apply logic that automatically uses the SEK **33 per person** flat-rate if it is beneficial.
* If the user selects a standard entertainment type and the VAT amount is between **6%** and **12%**, we show an information message about mixed VAT rates, and that it could be useful to split the purchase in two or more expenses. Splitting the expense is not mandatory; see it as a recommendation.
**Note**: If the user selects a standard entertainment type and the VAT amount is higher than **12%** of the total, we apply our legacy logic for restaurant entertainment, assuming the VAT rates are **12%** and **25%**. See **Restaurant meals with alcohol**.
**Entertainment types**
Each entertainment category can use one or more types of entertainment.
* **Lunch (takeaway)**
* **Dinner (takeaway)**
* **Refreshments (takeaway)**
* Lunch
* Dinner
* Refreshments
### Mixed VAT rates: 12% and 25% VAT
If the entertainment expense is for Meals with alcohol in a restaurant, the VAT amount will be made up of both **12%** and **25%** VAT. See **Restaurant meals with alcohol** above.
Mixed **6%**, **12%**, and **25%** VAT
In theory, it is possible to make a purchase involving all three VAT rates: **6%**, **12%**, and **25%**. In practice, this is unlikely to happen, but if it does, the purchase should be split into multiple expenses.For example:
* Lunch at a restaurant with food and alcohol, plus takeaway food for internal entertainment at the office: **6%**, **12%**, and **25%**.
If the receipt only shows a total VAT amount, it is not possible to reliably calculate the correct mix of VAT rates. If the VAT amount falls within the 6–12% range, we will display an information text suggesting that it may be beneficial to split the receipt into several parts.In the example above, this would be:
* One expense with **6%** VAT for the items taken back to the office.
* One expense with **12%** and **25%** VAT for the restaurant visit.
### Summary
* **Only 6% VAT:** Create an expense; use takeaway types for correct deductions.
* **Only 12% VAT:** Create an expense; do not use takeaway types.
* **Catering with alcohol:** Create an expense; use takeaway types.
* **Food and alcohol in a restaurant:** Create an expense, do not use takeaway types.
* **Other combinations:** Use the "Split receipt" function to divide the purchase into two or more expenses.
## Related articles
* [How do I switch between private mode and organisation?](/en/other-administrator/how-do-i-switch-between-private-mode-and-organisation)
* [How do I delete our organisation in the service?](/en/other-administrator/how-do-i-delete-our-organisation-in-the-service)
* [How do I change the logo and background image?](/en/other-administrator/how-do-i-change-the-logo-and-background-image)
* [How can I connect our organisation with Kivra Kvitton](/en/other-administrator/how-can-i-connect-our-organisation-with-kivra-kvitton)
* [What happens to the history if I delete a user?](/en/other-administrator/what-happens-to-the-history-if-i-delete-a-user)